FCA REGULATED · BUY TO LET SPECIALISTS

BUY TO LET SPECIALISTS

Whether you are buying your first investment property or expanding an existing portfolio, Verona Mortgages provides buy to let mortgage advice for individual landlords, limited companies and more complex property investments.

Access to a Wide Range of Lenders

Explore buy to let mortgage options from a wide range of lenders, including specialist providers.

Personal & Limited Company

Explore buy to let mortgage options whether you are purchasing personally or through a limited company.

Professional Mortgage Advice

Clear mortgage advice based on your circumstances, with support throughout the process.

Portfolio & HMO Mortgages

Mortgage options for portfolio landlords, HMOs and more complex property investment circumstances.

we help with

Buy to Let Mortgage Advice for Different Types of Landlords

Whether you are buying your first investment property or expanding an existing portfolio, we can explore buy to let mortgage options based on your property, circumstances and how you plan to invest.

buy to let mortgage broker advice verona mortgages
the process

How We Explore Your Buy to Let Mortgage Options

01

Tell Us About Your Investment

Tell us about the property, your existing portfolio and whether you are buying personally or through a limited company. This gives us a clear picture of your plans and circumstances.

02

We Explore Your Options

We explore buy to let mortgage options from a wide range of lenders, considering factors such as the property, rental income, deposit and lender criteria.

03

We Handle the Application

Once you decide how you would like to proceed, we manage your mortgage application and keep you updated as it progresses.

YOUR OPTIONS

Buy to Let Mortgages – Understanding Your Options

Buy to let mortgages are assessed differently from residential mortgages. The property, expected rental income, your circumstances and how you intend to own the property can all affect the mortgage options available.

Personal Name Buy to Let

Buying a rental property in your personal name is one route available to landlords. We can explore mortgage options based on the property, expected rental income and your circumstances.

Limited Company Buy to Let

If you are purchasing through a limited company, we can explore buy to let mortgage options from lenders that accept eligible company structures, including Special Purpose Vehicles (SPVs).

Portfolio & HMO Mortgages

Landlords with multiple properties or HMOs may need lenders with more specialist criteria. We can explore mortgage options based on your portfolio, property type and circumstances.

  • The most appropriate ownership structure will depend on your individual circumstances. Verona Mortgages provides mortgage advice; you should seek appropriate tax or legal advice when deciding how to own an investment property.
MEET THE ADVISERS

Speak With a Mortgage Adviser

Get to know the people behind Verona Mortgages. Our Mortgage Advisers provide personal mortgage support from your initial enquiry through to completion.

Yousef Gholami, Mortgage Adviser at Verona Mortgages

Yousef Gholami

Mortgage Adviser

Speak directly with Yousef about your mortgage options and next steps. Clear, straightforward advice based on your circumstances.
Daniel Mehrnia, Mortgage Adviser at Verona Mortgages

Daniel Mehrnia

Mortgage Adviser

Speak directly with Daniel about your mortgage options and next steps. Clear, straightforward advice based on your circumstances.
Mohammad Sharif Zadeh, Mortgage Adviser at Verona Mortgages

Mohammad Sharif Zadeh

Mortgage Adviser

Speak directly with Mohammad about your mortgage options and next steps. Clear, straightforward advice based on your circumstances.
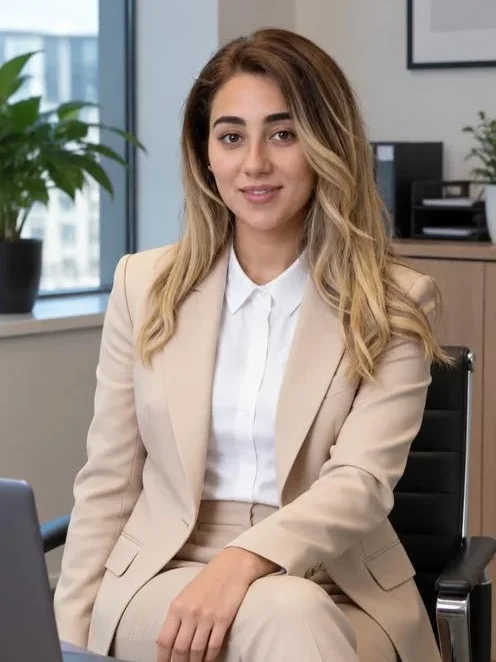
Shaghayegh Pouravin, Mortgage Adviser at Verona Mortgages

Shaghayegh Pouravin

Mortgage Adviser

Speak directly with Shaghayegh about your mortgage options and next steps. Clear, straightforward advice based on your circumstances.

FREQUENTLY ASKED QUESTIONS

Buy to Let Mortgage Questions, Answered

Buy to let mortgages work differently from residential mortgages. Here are answers to some common questions from landlords and property investors.

How much deposit do I need for a buy to let mortgage?

Buy to let mortgages generally require a larger deposit than residential mortgages. The amount you need will depend on the property, lender and your circumstances, so we can explore the options available to you.

Lenders may consider factors including the expected rental income, property value, your circumstances and their own affordability and lending criteria. The way this is assessed varies between lenders.

Yes, some lenders offer buy to let mortgages for eligible limited companies, including Special Purpose Vehicles (SPVs). The mortgage options available will depend on the company structure, property and lender criteria.

Yes, mortgage options may be available if you are buying your first investment property. Lender requirements vary, and some will also consider whether you already own your own home, your income and the expected rental income from the property.

Yes, there are lenders that consider HMOs and portfolio landlords, although these applications can involve more specialist criteria. The lender may consider the property as well as your wider portfolio and circumstances.

Yes. Landlords may consider remortgaging for a number of reasons, such as reviewing an existing mortgage or raising capital where appropriate. We can explore the mortgage options available for your property and circumstances.

Ready to Grow Your Portfolio?

Whether you are buying your first investment property, expanding your portfolio or reviewing an existing buy to let mortgage, talk through your mortgage options with an adviser.